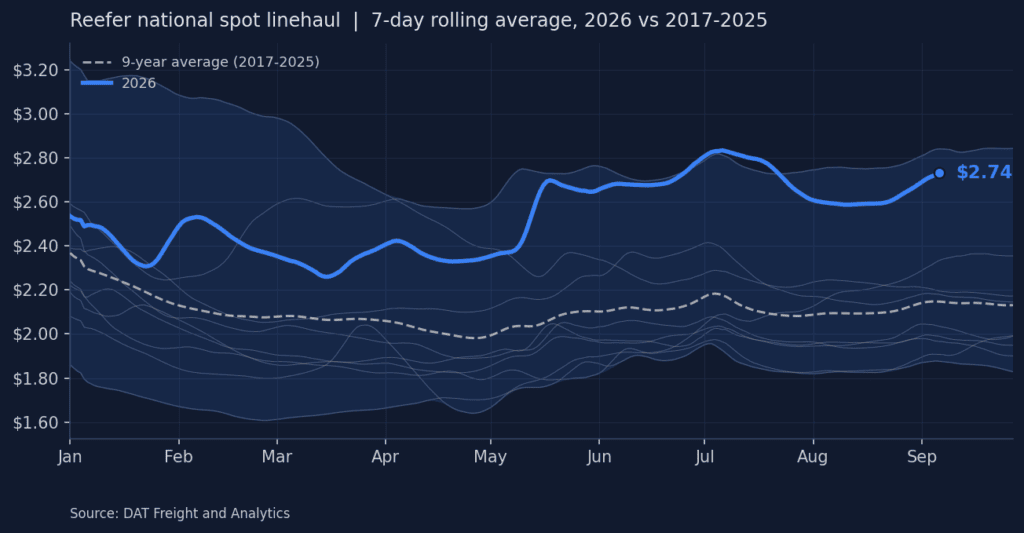
Reefer spot linehaul rates paid to carriers averaged $2.71 per mile last week, minus fuel, down 0.8%, or $0.02 per mile, from the week before. Rates ran 35.0%, or $0.70 per mile, year over year and held 26.6%, or $0.57 per mile, above the nine-year seasonal average of $2.14 per mile, near the top of the historical range.
All rates cited are linehaul only. They exclude fuel costs and surcharges unless otherwise noted.
Get the clearest, most accurate view of the truckload marketplace with data from DAT iQ.
Tune into DAT iQ Live, live on YouTube or LinkedIn, 10am ET every Tuesday.
Bellwether states
The 10 reefer bellwether states posted a moves-weighted outbound rate of $3.64 per mile last week, down 0.9%, or $0.03 per mile week over week and up 39.7%, or $1.03 per mile, year over year. The roster carried 40.3% of all U.S. state-outbound reefer loads, at the upper end of its 38 to 42% baseline.
Regional rate trends
| Reefer — Top 10 Origins by Rate Per Mile · Week Ending September 11, 2026 | ||||
|---|---|---|---|---|
| Rank | Origin Region | Avg RPM | WoW % | YoY % |
| 1 | Great Lakes | $3.32 | -0.4% | +39.2% |
| 2 | Upper Midwest | $3.27 | -3.7% | +36.0% |
| 3 | Ohio River | $3.26 | -1.0% | +43.1% |
| 4 | Lower Midwest | $3.22 | +1.4% | +39.3% |
| 5 | California | $2.95 | -0.5% | +31.6% |
| 6 | Upper Atlantic | $2.78 | -1.8% | +41.0% |
| 7 | Pacific Northwest | $2.78 | +2.1% | +26.5% |
| 8 | Southeast | $2.44 | -0.7% | +32.3% |
| 9 | Lower Mountain | $2.34 | +0.4% | +22.8% |
| 10 | South Central | $2.13 | -6.4% | +17.7% |
The top 10 origins carried 84.3% of all U.S. outbound loads moved in the week. Pacific Northwest led week over week at +2.1%, with the Midwest corridors staying near the top of the table.
Market conditions

Reefer saw the sharpest holiday pullback in freight of the three types. Load posts dropped 22.3% week over week as Labor Day interrupted produce shipping, yet they still ran 40.7% above last year. Truck posts gave back 12.1% on the week and sit 34.5% under a year ago. With loads falling faster than trucks over the short week, the load-to-truck ratio eased to 19.00 from 21.49 the week before last, more than double the 8.84 of a year ago.
Spot vs. contract
[Chart: contract vs. spot — insert last week’s image]
Contract rate figures were not included in last week’s Market Update, so the spot-versus-contract comparison is on hold. We’ll publish the updated spread, including where it currently sits relative to spot, as soon as contract data is available.
Short-term outlook

The 35-day DAT Rate Forecast puts reefer spot linehaul at $2.65 per mile in mid-October, within an uncertainty band of about plus or minus $0.06 per mile (2.4% of the forecast point). Across equipment, the reefer band ranks in the middle. That end-of-forecast rate stands about $0.57 per mile above the actual rate near the same date a year earlier ($2.08 per mile).
Freight demand outlook
South Texas breaks higher as California cools
South Texas is the one origin with real upward momentum last week. After a completely flat prior report, Mexico crossings through the Rio Grande Valley broke higher across the eastern and central lanes — Boston +14%, Miami +9%, Dallas +8%, Baltimore +7%, Chicago +4% — the clearest string of positive week-over-week moves on the entire board. Everywhere else, the weekly energy ran the other way: California’s carrot, coastal-vegetable and desert lanes softened, with Kern carrots into New York down -12% and Chicago down -10%, and the South & Central vegetable book off -11% into New York.
The year-over-year story is the same one it’s been all season: this is a market priced dramatically higher than a year ago, almost everywhere. Washington tree fruit out of Yakima is up 14% WoW and 16% YoY, the richest freight in the country — the Miami lane is booking $12,500–$13,500, up +58% over last September, and the Los Angeles lane is up a stunning +90% — even though every Yakima lane sat flat week-over-week. California citrus out of the South & Central district didn’t move a dollar on the week (every lane flat) yet runs +23% to +60% over 2025. Vidalia dry onions were pinned flat for another week while holding +18% to +40% YoY.
The takeaway for anyone pricing freight: South Texas is the lane book that moved last week, and it moved up. Beyond that, the board is drifting flat-to-soft on a weekly basis but sitting 20% to 90% above where it was a year ago — a market that reset higher earlier in the season and is now holding those levels rather than building on them.
Mexico crossings through South Texas — the week’s mover
The South Texas mixed-produce basket (peppers, tomatoes, limes, cucumbers, melons, cilantro and more) came off a dead-flat prior report and firmed on most eastern and central lanes last week. Boston led with a +14% jump; Miami, Dallas and Baltimore all posted mid-to-high single-digit gains. The one soft spot was New York, off -2%. On a year-over-year basis the district runs solidly higher wherever a 2025 comparison exists, topped by the long western haul into Los Angeles.
Yakima Valley & Wenatchee, Washington — still the richest board
New-crop apples (up 12% WoW), blueberries, peaches, pears and rhubarb anchor the basket, with cherries and prunes still riding the Miami lane. Every Yakima destination held flat week-over-week, but this remains the top-paying origin in the country and carries the widest year-over-year premiums anywhere — from +18% into Seattle to +90% into Los Angeles. Miami is the single richest lane on the board at $12,500–$13,500, a +58% premium over last September and one of only a handful of lanes clearing $12,000.
South & Central California — citrus frozen, vegetables sliding
The South & Central district splits into two baskets last week. Grapefruit, lemons and oranges did not move a single dollar week-over-week — every citrus lane printed flat — yet the district still runs +23% to +60% above last September, led by the long hauls into Atlanta, Seattle, Dallas and Boston. The separate vegetable basket (anise, artichokes, avocados, brassicas, celery, greens, lettuces, radishes, spinach) went the other direction, with the New York and Chicago lanes both dropping hard on the week.
California coastal & desert vegetables — soft on the week, rich on the year
The leafy and mixed-vegetable districts told one story last week: broadly flat-to-negative week-over-week, but running 24–43% above last year on every lane that has a 2025 comparison. Kern carrots took the sharpest weekly hits, while the desert (Imperial-Coachella) was mixed with a strong Atlanta print.
Eastern watermelons — deep into the tail, still above last year
Delmarva and North Carolina watermelons are running low and mostly slipping as the eastern melon deal moves through its late-summer tail. Delmarva still carries heavy year-over-year premiums — Atlanta and Chicago both +68% over last September — even as most weekly moves drifted negative. North Carolina has no prior-year counterpart in the report, so those lanes show the week’s move only.
Vidalia, Georgia — dry onions pinned flat
Vidalia dry onions were unchanged week-over-week on all nine destinations for another report, holding the same ranges as the week before last. Against last September, though, the district runs meaningfully higher across the board — from +18% into Atlanta to +40% into Dallas.
What this means for carriers, shippers & brokers
Carriers: Two places to aim. The Pacific Northwest remains the top of the market — Yakima tree fruit is pricing above $12,000 into Miami and $9,000–$11,500 into the eastern metros, with every lane 18–90% richer than a year ago, so if you can get equipment into Washington for new-crop apples and pears, that’s the strongest per-load economics on the board. The fresher opportunity is South Texas: crossings firmed on most eastern and central lanes last week, so the Valley is a market with weekly wind at its back rather than one that’s stalling. California coastal produce still pays well on the long eastern hauls (Salinas and Santa Maria into Baltimore and Philadelphia clearing $10,000, Kern into Philadelphia near $10,900), but the weekly trend there has turned soft — don’t bank on further upside off these levels. The eastern watermelon lanes out of Delmarva and North Carolina are low-dollar and thinning; treat them as fill freight, not anchor loads.
Shippers: If you’re moving out of South Texas, the window to lock rates before they climb further is now — the eastern lanes just moved up and momentum is pointing the same way. Washington tree fruit shippers should budget for elevated rates and book early rather than chase; you’re paying a steep premium over last year on essentially every lane. The California side is your relief valve: carrot, leafy and desert rates out of Kern, Salinas, Santa Maria, Oxnard and the Imperial-Coachella district have stopped climbing and several eased last week, so there’s less pressure to overpay right now. Vidalia onion shippers continue to enjoy a flat, predictable market that makes forward planning easy.
Brokers: The divergence to trade is South Texas versus California. South Texas is the one origin with genuine weekly momentum, so protect margin there — the eastern and central lanes are moving up and shippers will feel it. Across California, the flat-to-negative week gives you room to hold the line with shippers without lanes running away from you. Yakima stays the premium book and demands margin discipline on new-crop tree fruit. And where a lane shows a large YoY number but a flat or negative week — the CA citrus book, Vidalia, and the western South Texas lanes — that’s a market that reset higher earlier in the season and is now holding; price to the current week, not to the year-ago anchor. The eastern melon deals are winding down, so expect fewer loads and softer rates out of Delmarva and North Carolina as those regions finish out.