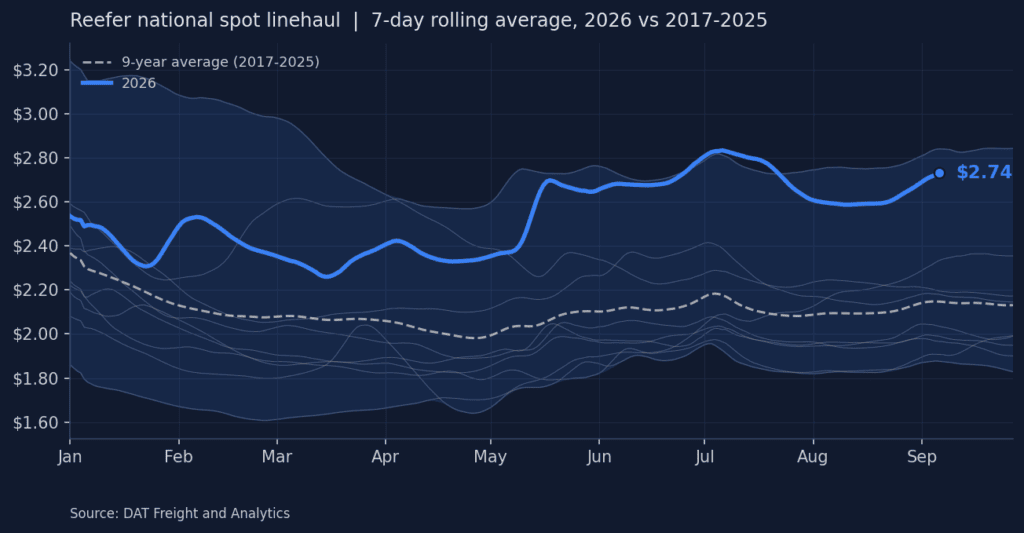
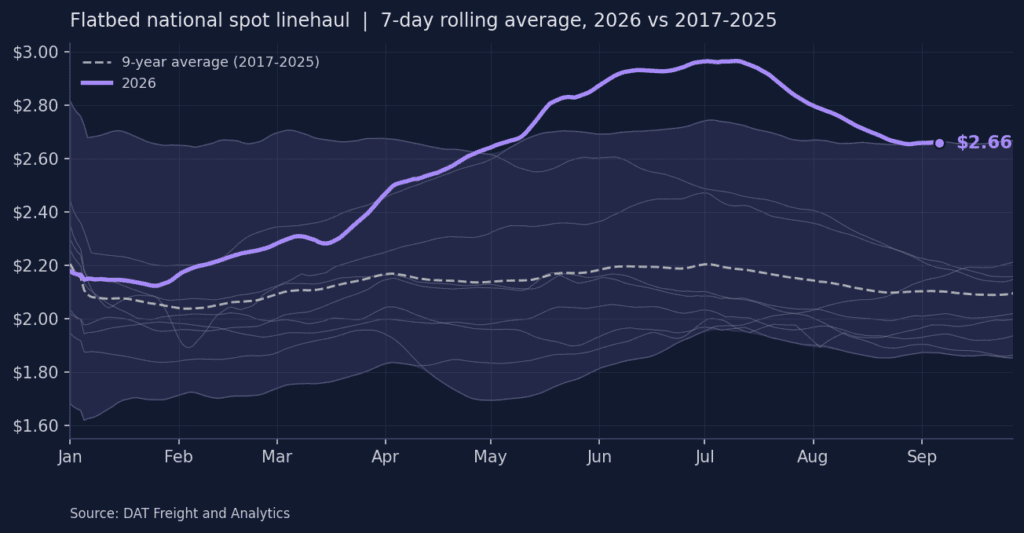
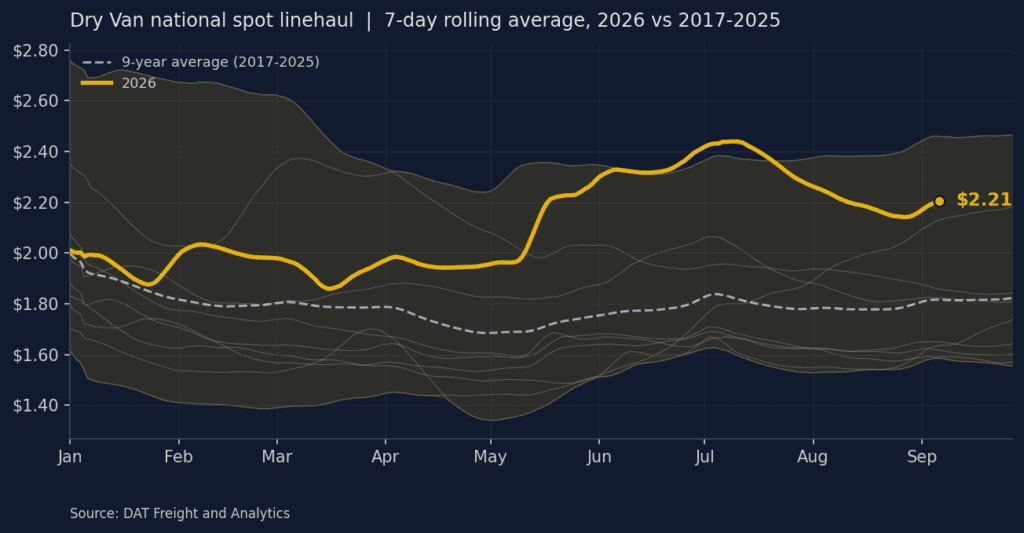
Dry van spot linehaul rates paid to carriers averaged $2.20 per mile last week, minus fuel, down 0.6%, or $0.01 per mile, from the prior week. Rates ran 34.2%, or $0.56 per mile, year over year and held 21.0%, or $0.38 per mile, above the nine-year seasonal average of $1.81 per mile, near the top of the historical range.
All rates cited are linehaul only. They exclude fuel costs and surcharges unless otherwise noted.
Get the clearest, most accurate view of the truckload marketplace with data from DAT iQ.
Tune into DAT iQ Live, live on YouTube or LinkedIn, 10am ET every Tuesday.
Bellwether states
The 10 dry van bellwether states posted a moves-weighted outbound rate of $2.94 per mile last week, down 0.3%, or $0.01 per mile week over week and up 39.6%, or $0.84 per mile, year over year. The roster carried 35.3% of all U.S. state-outbound dry van loads, in line with its recent baseline near 35%.
Regional rate trends
| Dry Van — Top 10 Origins by Rate Per Mile · Week Ending September 11, 2026 | ||||
|---|---|---|---|---|
| Rank | Origin Region | Avg RPM | WoW % | YoY % |
| 1 | Ohio River | $2.52 | -1.0% | +36.5% |
| 2 | Great Lakes | $2.51 | -0.4% | +34.9% |
| 3 | California | $2.38 | -1.2% | +27.4% |
| 4 | Lower Midwest | $2.27 | +0.4% | +31.1% |
| 5 | Upper Atlantic | $2.25 | -0.6% | +31.5% |
| 6 | Lower Atlantic | $2.25 | +0.1% | +35.7% |
| 7 | Carolinas | $2.17 | -0.1% | +35.7% |
| 8 | Southeast | $2.14 | -1.1% | +32.7% |
| 9 | South Central | $1.95 | -2.1% | +23.3% |
| 10 | Florida-So Georgia | $1.44 | -3.0% | +29.1% |
The top 10 origins carried 87.7% of all U.S. outbound loads moved in the week. Lower Midwest led week over week at +0.4%, as rates held broadly firm across the leading origins through the holiday week.
Market conditions

Dry van activity pulled back over the Labor Day week, with the holiday Monday trimming posting volume on both sides of the market. Load posts fell 18.0% week over week, a seasonal drop tied to the holiday, though they held 23.0% above the same week last year. Truck posts eased 14.1% on the week and remain 40.2% below a year ago. Because freight receded a touch faster than capacity, the load-to-truck ratio slipped to 10.95 from 11.47 a week earlier, still well above the 5.33 of a year ago.
Short-term outlook

The 35-day DAT Rate Forecast puts dry van spot linehaul at $2.20 per mile in mid-October, within an uncertainty band of about plus or minus $0.08 per mile (3.5% of the forecast point). Across equipment, the dry van band ranks widest. That end-of-forecast rate stands about $0.52 per mile above the actual rate near the same date a year earlier ($1.68 per mile).
Freight demand outlook
The real truckload signal in the August ISM report isn’t in the headline, it’s in what the panelists themselves said about where freight is being created and moved. The line carriers should circle came from a transportation-equipment producer who described volume as steady but flagged that a key customer is relocating production from U.S. plants to Mexico. A machinery panelist reinforced the same instinct, saying they’ve pushed more sourcing offshore to blunt cost increases. That’s a nearshoring drumbeat freight networks can’t ignore: it pulls volume onto cross-border lanes, the Laredo and South Texas gateway in particular, and reshapes domestic linehaul rather than simply adding to it. Running alongside that, electronics and miscellaneous-manufacturing respondents describe an AI-driven supply scramble, with semiconductors, photonics, connectors, and government orders “expanding significantly,” while calling availability and lead times the worst since the post-COVID stretch. That combination is generating high-value inbound and project freight tied to data-center and electrical-infrastructure buildout, even in an otherwise cooling factory environment.
The caution in these comments points downstream, and it’s the part truckload demand hinges on. Several respondents connected relentless input-cost inflation, steel, aluminum, energy, tariff-driven, to a fear that higher prices eventually erode consumer purchasing power and soften end demand. A primary-metals panelist summed up the mood, describing demand as a seesaw and their own ability to forecast as shrinking. For truckload, that reads as a market where freight is steady but choppy and hard to plan around: consistent volume from industrial and infrastructure shippers, set against a growing question mark over the consumer-goods replenishment cycle that fills dry vans. Worth noting, freight itself sits on ISM’s list of commodities rising in price for a sixth straight month, a reminder that in a sideways-demand market, it’s capacity discipline, not a demand surge, doing the work on rates.